Other institutions would like to know why. You are required to show it.
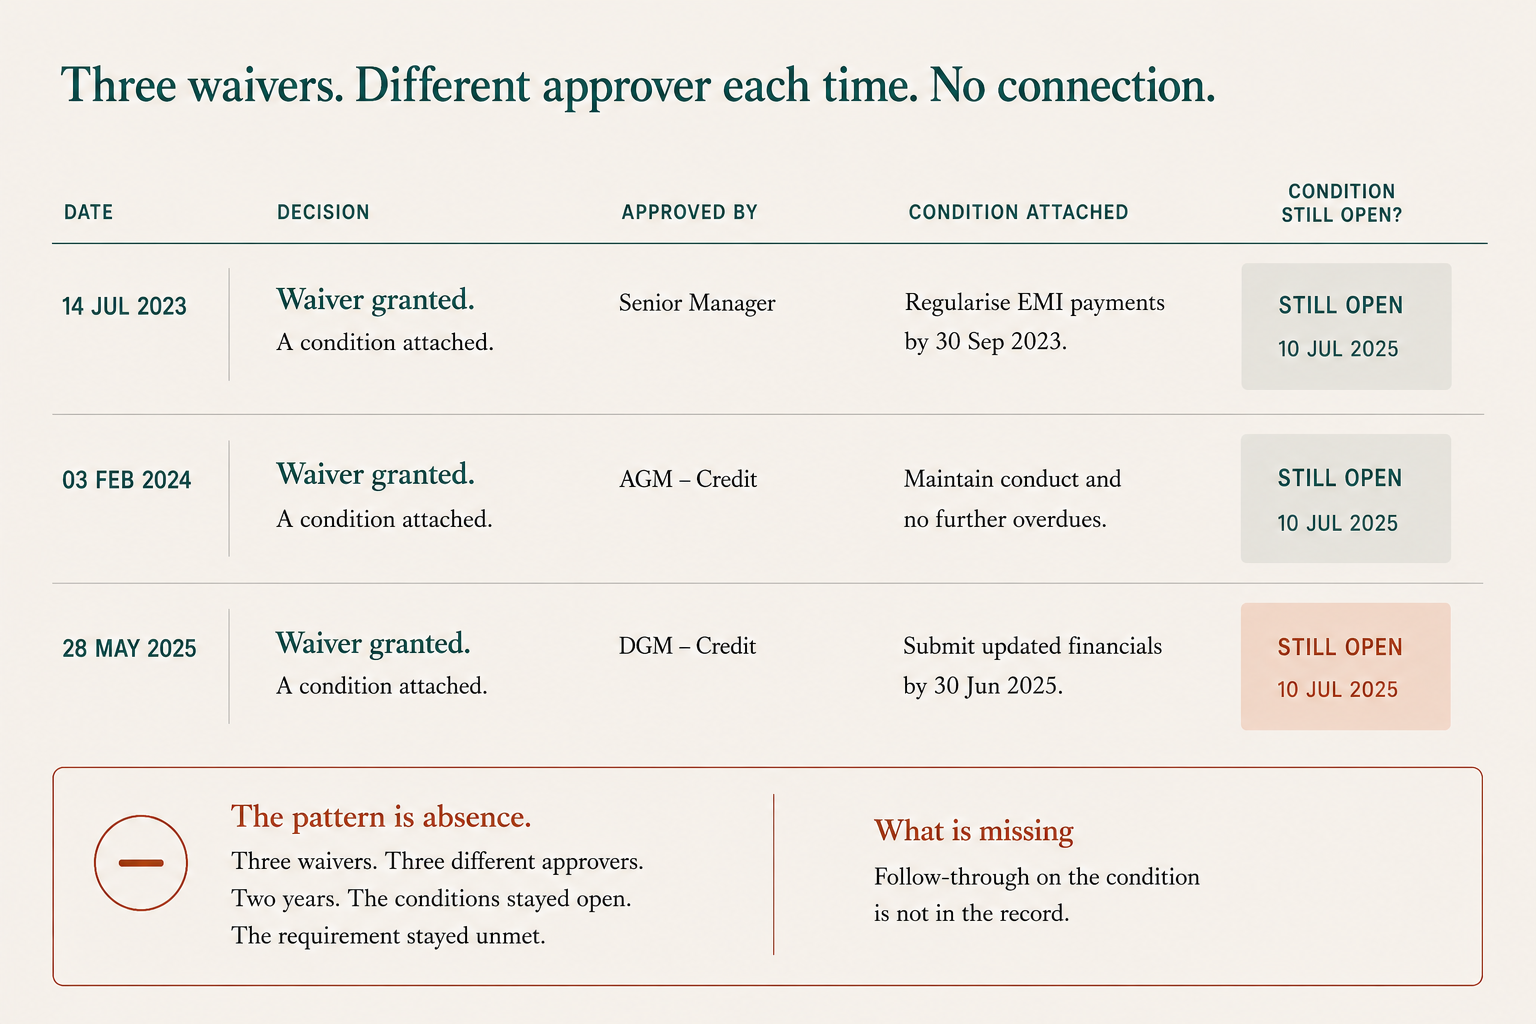
A waiver granted three times, by three people who never knew about each other.
Not an exception any more. Policy that nobody wrote down and nobody approved.
Why nobody catches this today
The first waiver was reasonable. So was the second, eighteen months later, granted by someone who had never seen the first. The third was granted by a third person.
Each was recorded. None was counted. The exception register holds the formal ones. The one agreed on a call, approved within authority, never entered - that one is only in the conversation.
Nobody was looking for the third instance, because nobody knew there had been a first.
What else dhi looks for
A credit decision at committee for three sittings with no sanction, no declination, no dated deferral. A deferral nobody dated is invisible.
A sanction condition open past two review cycles. Attached at approval, never met, never waived, never lapsed.
Coverage transferred with open facilities and no handover recorded. The book moved. The reasoning did not.
A review date passed with no rating recorded. A mandated periodic review that did not happen is a supervisory finding waiting to be made.
What dhi will not do here
No credit score. No risk rating. No recommendation.
There is nothing for your model risk function to validate, because nothing of that kind is produced. It surfaces. It does not decide.
And no finding is ever about a person. Findings describe decisions, exposures and processes - a person is not a permitted subject, enforced in the data model rather than promised in a contract.
Domain model and pattern library complete.
Live design partnerships in Indian banking.
Deploy dhi in your credit or risk operations
Run a pilot in shadow mode in your next quarterly credit committee.